Leapfrog Economics: What Ethiopia's Mobile Money Surge Reveals About the Future of Financial Infrastructure
For most of the twentieth century, financial inclusion followed a recognizable sequence: physical bank branches first, then ATM networks, then debit infrastructure, and eventually—decades later—digital payment interfaces layered on top of the whole architecture. This sequence made sense in the economies where it developed. It makes far less sense in Ethiopia, where a population of more than 120 million people has bypassed much of that progression entirely and arrived at mobile-first finance through a fundamentally different route.
What is happening in Ethiopia's payment ecosystem is not simply a technology story. It is an economic reorganization with implications that extend well beyond the Horn of Africa—and American financial institutions and policymakers would be prudent to study it carefully.
The Scale of the Shift
Ethiopia's mobile money landscape has expanded at a pace that surprised even its most optimistic advocates. Telebirr, the mobile financial service launched by Ethio Telecom in 2021, registered more than 40 million users within its first two years of operation—a rate of adoption that rivals the fastest-growing fintech platforms in any market, anywhere in the world. This growth did not occur in a vacuum of competition; it occurred in a country where commercial bank branch density remains among the lowest in sub-Saharan Africa and where, until recently, the financial sector was closed to foreign investment by law.
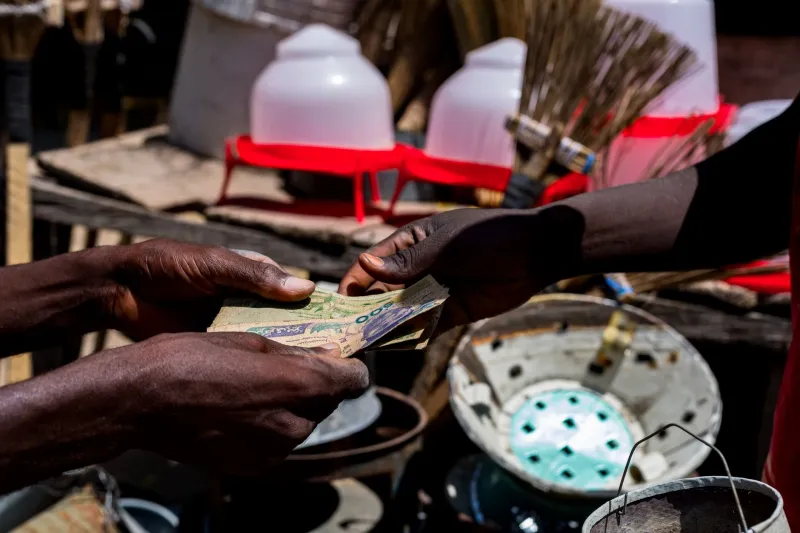
The implications of that context are significant. Telebirr and the mobile money services emerging alongside it are not supplements to an existing banking infrastructure. They are, for tens of millions of Ethiopians, the banking infrastructure—the primary mechanism through which wages are received, merchants are paid, remittances are delivered, and savings are held. This is financial inclusion not as an aspirational policy objective but as a lived economic reality, constructed in the absence of the legacy systems that older financial architectures took decades to build.
Why Leapfrogging Happens Here
The term "leapfrogging" is used frequently in development economics, often loosely. In the Ethiopian case, the conditions that enabled it are worth examining with some precision, because they are not accidental.
Mobile phone penetration in Ethiopia has grown dramatically over the past decade, driven by falling handset costs and expanding network coverage under Ethio Telecom's infrastructure investment program. A population that lacked reliable electricity access a generation ago now has meaningful smartphone or feature phone connectivity in urban centers and an increasing share of rural areas. The handset, not the branch, became the logical point of financial contact.
Simultaneously, Ethiopia's regulatory environment—historically conservative regarding financial sector liberalization—created a peculiar opening. The government's decision to allow Ethio Telecom to operate mobile money services before fully opening the sector to foreign commercial banks meant that the mobile-first model was not competing against entrenched banking incumbents. It was filling a space those incumbents had not occupied. The competitive dynamics that slow mobile money adoption in markets with mature banking sectors simply did not apply.
Finally, the structure of Ethiopia's economy—characterized by large volumes of small transactions, significant internal remittance flows between urban workers and rural families, and a merchant base dominated by micro and small enterprises—is precisely the environment in which mobile money generates the greatest marginal value. The product fit is not incidental; it is structural.
Blockchain, Cross-Border Flows, and the Next Layer
Beyond mobile money's domestic expansion, a second development is beginning to reshape Ethiopia's financial landscape in ways that carry distinct implications for global fintech strategy. Cross-border payment infrastructure, long one of the most friction-laden segments of African financial services, is being partially reorganized through blockchain-adjacent technologies and bilateral digital payment agreements.
The Ethiopian diaspora in the United States, which sends an estimated two to four billion dollars in remittances annually, has historically relied on wire transfer services that extract significant fees from both sender and recipient. Emerging digital remittance platforms—some built on distributed ledger architecture, others on more conventional digital rails—are beginning to reduce those costs while increasing transfer speed. The economic stakes are not trivial: every percentage point reduction in remittance fees translates into hundreds of millions of dollars retained in Ethiopian households rather than extracted by intermediaries.
For Western fintech companies watching this space, the lesson is not simply that Ethiopia represents an underserved market—though it does. The more consequential observation is that the payment architecture being built in Ethiopia, and across sub-Saharan Africa more broadly, is being designed from the ground up for the transaction volumes, currency volatility, and connectivity constraints characteristic of emerging markets. The resulting systems may, in certain respects, be more adaptable and more efficient than payment infrastructure built atop the legacy frameworks that American and European financial institutions inherited.
What American Institutions Are Missing
The dominant American response to Africa's mobile money expansion has been a combination of philanthropic interest and cautious investor attention. Both responses, while not without value, tend to frame the phenomenon as a development story rather than a strategic and commercial one. This framing carries real costs.
For American financial institutions, Ethiopia's mobile money ecosystem represents both a partnership opportunity and a competitive reference point. Companies like Stripe, PayPal, and the constellation of US-based fintech startups competing in the digital payments space are operating in markets where mobile-first payment behavior is increasingly the norm, not the exception. Understanding how Telebirr and its counterparts designed for that behavior—at scale, with limited connectivity, in a multilingual regulatory environment—is commercially relevant information.
For American policymakers, the strategic dimension is equally important. Financial infrastructure shapes economic relationships. The platforms through which Ethiopian businesses and consumers transact will influence which currencies, which clearing systems, and which institutional partnerships become normalized in the Ethiopian economy over the coming decades. The United States has significant interests in the direction of that normalization—interests that are not well served by treating Africa's digital payment revolution as a peripheral curiosity.
Building the Right Framework
A coherent American policy response to Ethiopia's fintech evolution would involve several components. Regulatory engagement through the Treasury Department and the Consumer Financial Protection Bureau could facilitate the entry of American fintech companies into Ethiopian and broader East African markets on terms that support interoperability with local systems rather than displacing them. Investment facilitation through the Development Finance Corporation could support the infrastructure layer—data centers, connectivity, identity verification systems—on which sustainable financial inclusion depends. And diplomatic engagement could prioritize digital payment standards in US-Africa trade discussions, creating frameworks that serve both American commercial interests and African financial sovereignty.
Ethiopia's mobile money surge is not a story about a poor country catching up. It is a story about a different kind of financial architecture emerging under different constraints and producing different results. The American institutions that understand this distinction earliest will be best positioned to engage with it productively. Those that continue to view it through a purely developmental lens will find themselves, eventually, observing from the outside a market they could have helped to shape.